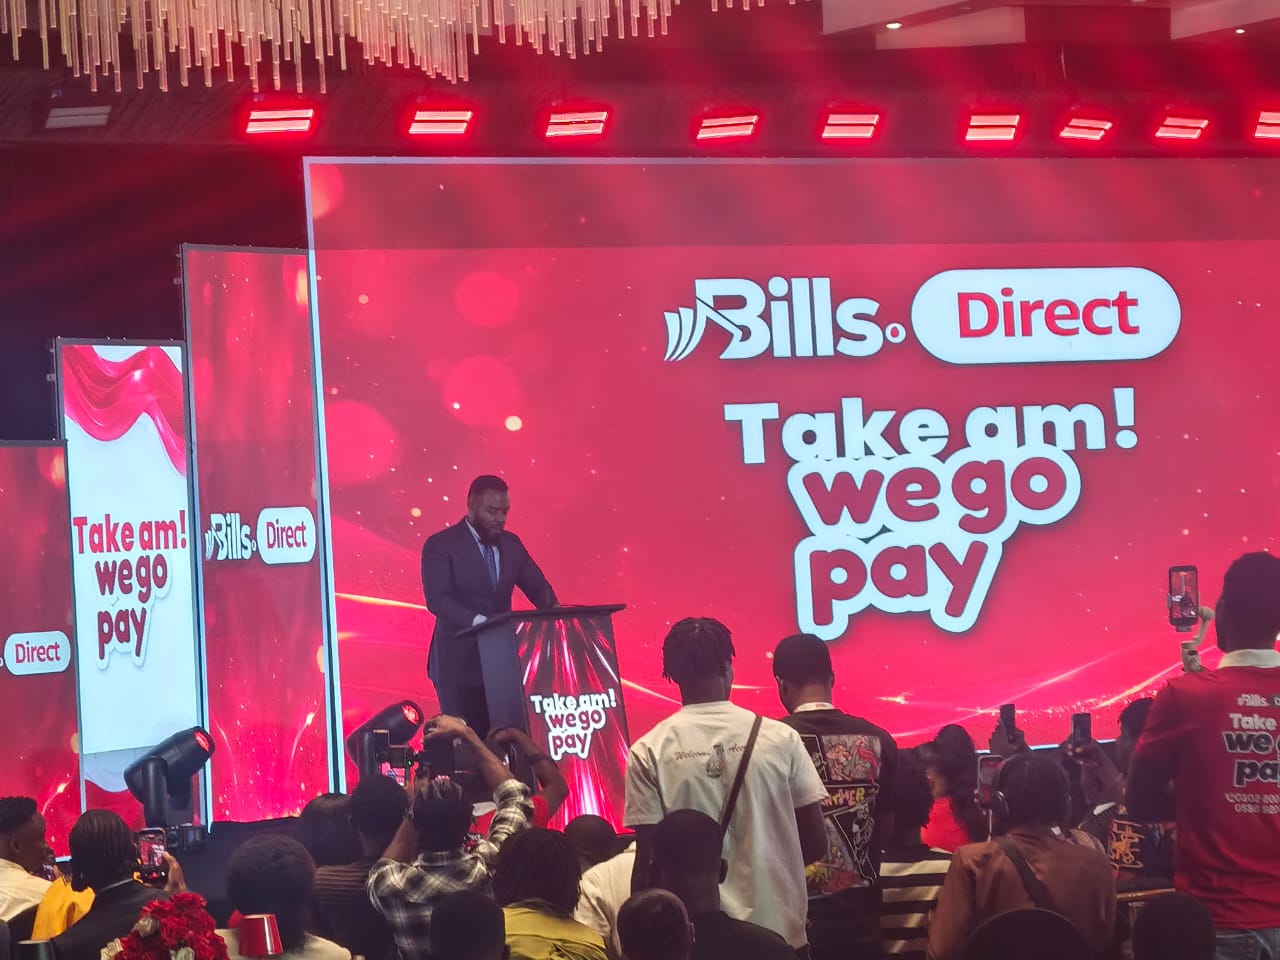

Bills Micro-Credit Ltd is positioning itself to become a major player in Ghana’s consumer financing market, with plans to expand access to cash loans and financing for household products, equipment and other essential items with the launch of its hire-purchase and flexible payment initiative ‘Bills Direct Product.’
The company says it wants to build a comprehensive financing portfolio that responds to the needs of individuals, entrepreneurs and businesses, while establishing Bills as a household name within the next year.
Its Chief Executive Officer, Romeo-Richlove Elorm Kweku Seshie, speaking during the launch of Bills Direct, indicated that the ambition was to make the company a reliable financing option for Ghanaians seeking support to meet personal and business needs.
“My expectation is to build a very heavy portfolio. I’m expecting to satisfy the needs of everybody out there, both through cash and financing consumer products,” he said.
He added that the long-term goal was for consumers to think of Bills whenever they needed financial assistance or wanted to acquire products through flexible payment arrangements.
He called for stronger corporate governance, effective management and responsible lending practices as the company positions itself for expansion across Ghana.
He said the company’s next phase of growth would depend not only on increasing the volume of loans and financial transactions but also on its ability to respond to changing customer needs and deliver measurable improvements in the lives and businesses of its clients.
Mr Seshie stressed that assessing the company’s performance must go beyond transaction figures and financial values to examine the quality of management, the impact of financing on customers and the effectiveness of its business operations.
He described good corporate governance as a critical foundation for building confidence and ensuring the long-term sustainability of Bills Micro-Credit Ltd.
Drawing on the company’s more than 30 years of experience and established presence in Ghana’s credit market, he expressed confidence in the leadership and management team to expand its operations and strengthen its presence across the country.
He encouraged the company to continue investing in sound governance structures, management capacity and responsible business practices to support its growth ambitions.
Mr Seshie also highlighted the broader role of microfinance institutions in supporting economic development, arguing that access to credit should translate into stronger businesses, improved productivity and expanded economic opportunities.
He noted that the future of microfinance should not be measured solely by how many people receive loans but by the opportunities that access to finance creates.
According to him, responsible financing has the potential to strengthen businesses, support entrepreneurs and enable individuals to participate more effectively in economic activities.
On his part, the Founder of Bills and Quick Angels Limited, Richard Nii Armah Quaye, said the company’s consumer financing model was intended to address the purchasing-power gap that limits people’s ability to acquire assets and essential items.
He argued that differences in purchasing power contribute to the varying living standards among people in the upper, middle and lower income groups.
According to him, Bills Direct is designed to bridge that gap by allowing consumers to acquire properties, products and other conveniences and pay for them over time, rather than waiting until they have accumulated the full purchase price.
The initiative also has implications for small and medium-sized enterprises (SMEs), which often struggle to meet customer demand because of limited working capital.
Mr Seshie also emphasised the importance of sound governance, effective management and customer-focused financing as the company seeks to expand its operations.
He said the company’s existing experience and presence in the credit market provided a foundation for its next phase of growth, while encouraging continued investment in institutional capacity and responsible business practices.
Nana Kwame Agyenin Boateng, President of the Ghana National Chamber of Commerce and Industry (GNCCI), also highlighted the financing challenges confronting small businesses, noting that many entrepreneurs have customers but lack the funds needed to purchase stock, expand operations or meet growing demand.
He called for responsible credit arrangements that take into account borrowers’ repayment capacity, with particular attention to women-owned businesses, young entrepreneurs, traders and other small-scale operators.
He also stressed the importance of proper credit assessment, fair repayment arrangements and sound lending practices to protect both borrowers and financial institutions.
The comments underscored the role of microcredit beyond the provision of loans, particularly in helping businesses improve productivity, strengthen operations and respond to market opportunities.
How Bill Direct Works
Customers walk into participating partner stores to select items such as mobile phones, televisions, fridges, furniture, or motorbikes, and invoice is raised.
Bills Direct pays the vendor directly.
Customers take their purchases home immediately and repay in weekly or monthly installments over a 3- or 6-month period.
Key Benefits & Requirements
No Down Payment required.
No Account Opening necessary.
No Collateral needed.
Requirement: A valid Ghana Card and a steady source of income/business (open to salaried workers, traders, students, market sellers, and self-employed individuals).
For Bills, the expansion represents an effort to connect consumer financing with enterprise development, giving individuals greater purchasing flexibility while helping businesses access the resources they need to grow.